I have two prior Inspire Medical Systems ($INSP) stock analysis videos on record — one from May 2026 and one from June 2026 — both calling Inspire a buy while the stock was priced like a company in decline. Since then, INSP is up roughly 80%. The thesis was never complicated: Inspire's financials kept growing while the market kept selling the stock off. That kind of dislocation, where negative sentiment drags a share price down even as the underlying business gets stronger, tends to resolve itself once the sentiment fades.
The Inspire Medical Systems Thesis: 80% Higher, Still Cheap
Even after an 80% rally, I think Inspire Medical Systems stock is still undervalued relative to where its fundamentals actually sit. Using the financial data tools on youdomo.com, you can pull Inspire's full stock price and fundamentals history in one place. Inspire hit an all-time high of $325 per share back in July 2023. Since then, the stock has fallen all the way down to around $72 — even as revenue, gross profit, and net income have all continued to climb.
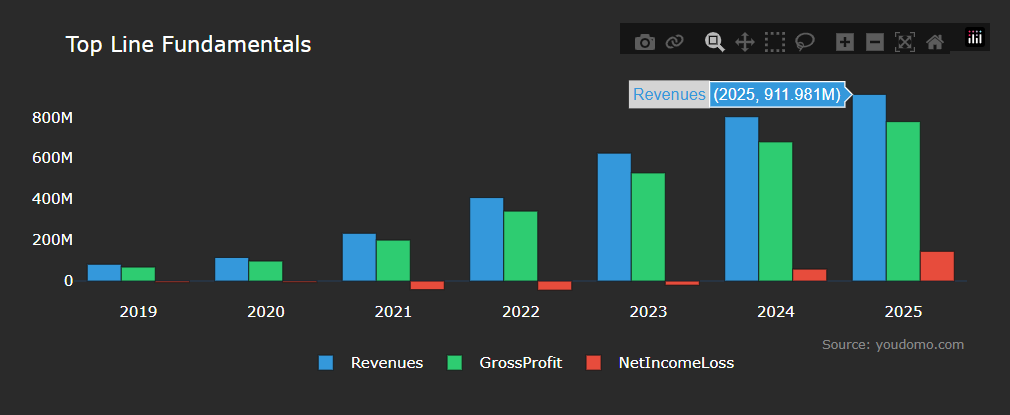
Here's the disconnect that makes this stock interesting: at roughly $70 per share, Inspire Medical Systems trades at close to the same market capitalization it held back in 2019, when the company generated only $82 million in revenue and was posting negative net income. In 2025, Inspire generated $911 million in revenue and $145 million in net income. A company doing more than 10x the revenue, and now solidly profitable, is priced like it was six years ago when it was unprofitable and a fraction of the size. That mismatch is the entire thesis behind this Inspire Medical Systems stock analysis.
Inspire's Financials: Growing While the Stock Fell
Inspire became a net income positive company starting in 2024 — a meaningful inflection point for a medical device company that spent years investing heavily in commercial expansion. The chart below shows Inspire's top-line fundamentals from 2019 through 2025: Revenue, Gross Profit, and Net Income all trending in the same direction — up — regardless of what the stock price was doing over that same stretch.
The Real Story Behind Inspire's Q2 2026 Revenue Decline
Part of the negative sentiment weighing on Inspire Medical Systems stock traces back to a specific line in the Q2 2026 report: management cited "coding and reimbursement disruption" as a driver of a 7.6% year-over-year revenue decline for the quarter. For anyone unfamiliar with the term, coding and reimbursement refers to the process by which a medical treatment, device, or procedure is assigned a specific billing code so that it can be paid for by insurers — whether private payers or government programs like Medicare and Medicaid.
This coding issue is not, at its core, an Inspire-specific failure — it's a broader healthcare industry billing problem. When Inspire launched Inspire V, its newest-generation sleep apnea device, the company had been billing it under an existing CPT code. That code, used for approximately 10,000 Inspire V cases in 2025, is no longer available for Medicare reimbursement, which forced physicians and hospitals to scramble for alternative coding pathways. That's a bloated, bureaucratic healthcare system problem — not evidence that demand for Inspire's therapy is drying up. Once this coding issue resolves, and there's a reasonable path for it to, Inspire should regenerate its prior pace of revenue growth.
What Does Inspire Medical Systems Actually Do?
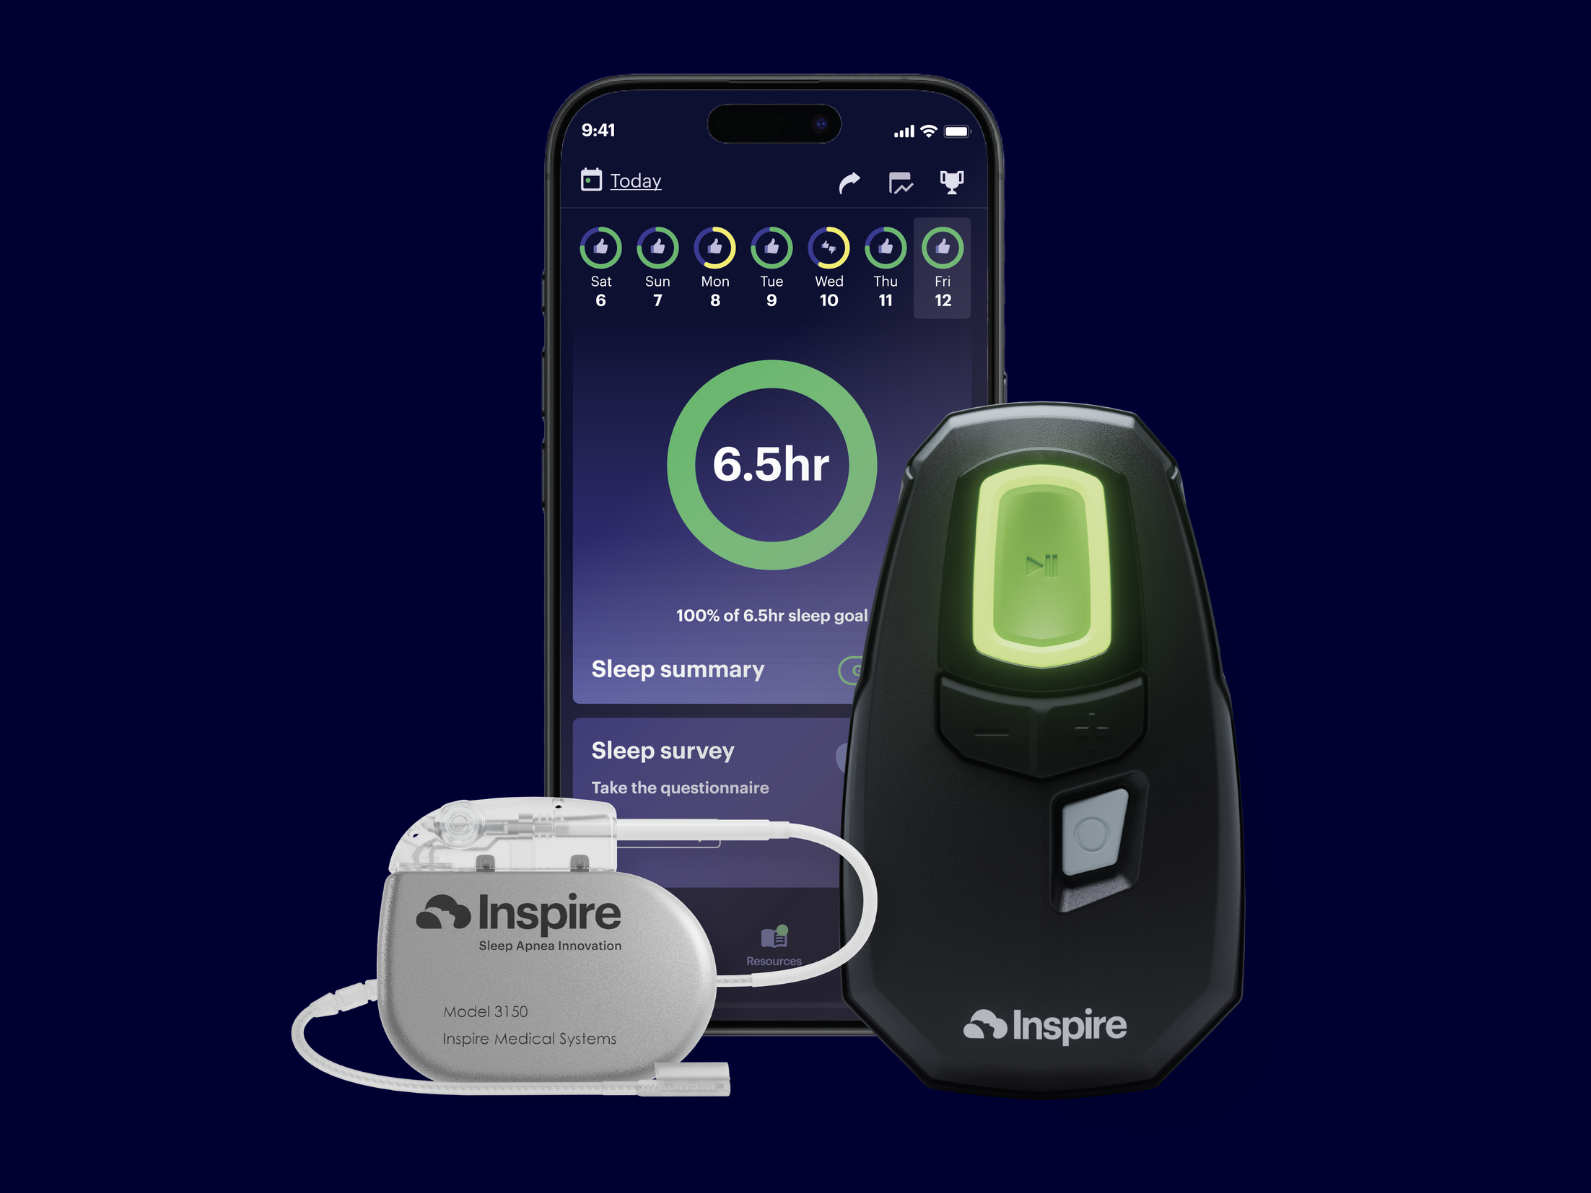
Inspire Medical Systems ($INSP) is a medical technology company that makes an implantable device to treat obstructive sleep apnea (OSA) — specifically built for patients who can't tolerate, or haven't had success with, CPAP (continuous positive airway pressure) machines, which remain the standard first-line treatment for sleep apnea. Instead of a mask and hose, Inspire's system — including the newest-generation Inspire V — works by detecting a patient's breathing pattern during sleep and delivering mild stimulation to keep the airway open, all controlled through a small handheld remote and companion app.
Price Target: A Conservative Path to $100 Per Share
I expect Inspire Medical Systems stock to stay volatile in the near term — a pullback wouldn't be surprising after an 80% run, and the coding disruption is a legitimate near-term overhang on revenue growth. But I still think INSP has meaningful room to run from here. Management's 2026 revenue guidance sits between $835 million and $875 million. Historically, Inspire has traded at a rich Price-to-Sales (P/S) multiple around 47x. Even using a far more conservative 10x P/S multiple against $875 million in projected 2026 revenue, spread across roughly 87 million shares outstanding, implies a share price near $99 — upside from current levels without assuming any return to Inspire's historical valuation premium.
A company growing revenue toward $875 million, sitting on a resolvable billing issue rather than a demand problem, priced like it's still 2019 — that's the setup.
The Obstructive Sleep Apnea Market Through 2050
Beyond the near-term coding noise, Inspire Medical Systems sits in front of a large and growing addressable market. A study published in The Lancet Respiratory Medicine, cited by ResMed, projects that by 2050, obstructive sleep apnea will affect nearly 77 million U.S. adults — a relative increase of nearly 35% from 2020 levels, impacting an estimated 46% of adults aged 30 to 69. A meaningful share of these patients either can't tolerate CPAP or find it ineffective, which is exactly the population Inspire's implantable therapy is designed to serve. Given that demographic tailwind, along with the likelihood of coding resolution and potential multiple expansion as sentiment normalizes, I'm raising my price target on Inspire Medical Systems to $100 per share.
How I Found Inspire Medical Systems
I originally discovered Inspire Medical Systems through the Value Finder on youdomo.com. The Value Finder automatically screens for stocks trading at discounted valuation multiples while growing their financials faster than their competitors, so you can skip the manual research and let the tool surface dislocated opportunities like this one.
Final Verdict: Is INSP Stock a Buy in 2026?
Inspire Medical Systems is up roughly 80% since I first flagged it, and it's still trading near the same valuation it held in 2019 despite generating over $900 million in 2025 revenue and turning solidly net income positive. The Q2 2026 revenue decline looks like a healthcare billing and coding disruption tied to Inspire V's transition off an expired CPT code — not a breakdown in patient demand — and it's the kind of issue that resolves over time rather than compounds. With a conservative price-to-sales model pointing toward $99-$100 per share and a sleep apnea market projected to grow toward 77 million U.S. adults by 2050, I'm raising my price target to $100. Expect volatility in the near term after this run, and this is not financial advice.
This article is for information and education only and is not financial advice. Do your own research, or consult a licensed financial advisor, before making investment decisions. Past performance does not guarantee future results. I may hold a position in $INSP at the time of publishing.